cc.web.local

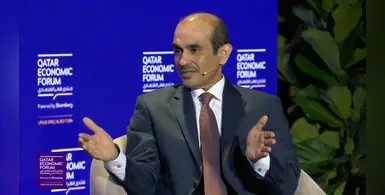
HE Saad Sherida Al-Kaabi , Qatar’s Energy Minister, CEO and president of QatarEnergy speaking at the Qatar Economic Forum. (Image source: QatarEnergy)

Qatar now expects production from its massive North Field East LNG expansion to start up in 2027, according to HE Saad Sherida Al-Kaabi , Qatar’s Energy Minister, CEO and president of QatarEnergy

Speaking at the Qatar Economic Forum, Powered by Bloomberg: UNGA Special Edition 2026 in New York, the Minister said the first production train at North Field East – the initial phase of Qatar’s LNG expansion – is expected to come online in the first half of 2027 as shipping disruptions in the Strait of Hormuz slow projects across the country’s economy. It had previously been expected to start production this year.

Tightening LNG supplies

The world's largest single non-associated gas field, the North Field, spanning over 6,000 sq. km, represents 20% of the world's total gas reserves. Qatar’s North Field expansion projects aim to raise LNG production capacity to 142mn tons per annum (MTPA) before the end of this decade. The North Field South project – the second phase of the expansion – is slated to come online in 2028, Al-Kaabi said – but these timings will depend on what happens in the Hormuz Strait and the ability to get facilities coming in.

The timeline reinforces the expectations that the near-closure of the Strait of Hormuz due to the Iran war threatens to tighten global LNG supplies for years, Bloomberg comments. Disruptions have already cut LNG supplies from Qatar — the world’s second largest LNG exporter and a key supplier to both the Asian and European markets — sending spot prices surging to the highest level since 2022 in Asia and Europe.

Qatar’s Ras Laffan plant, which produced nearly a fifth of the world’s LNG before the war began in February, can resume operations at undamaged parts of the facility “within a couple of weeks” when Hormuz reopens, the Minister said. The attack on Ras Laffan early on in the conflict resulted in damage to two LNG trains and Shell’s GTL plant, prompting Qatar to declare force majeure to its affected buyers.

“Repairs on the GTL train will be concluded in the first quarter of 2027. However, it will take three years for repairs on the two LNG trains,” the Minister said. 

Qatar is currently exporting a very small amount of LNG through the Strait, Al-Kaabi said, adding that Doha has decided not to build bypass pipelines.

“LNG, our main export commodity, cannot be transported by pipelines. We will have to transport it by pipelines as gas and then liquify it at the receiving terminal, wherever that may be. This means we are building reductant facilities to the ones we are already building in Qatar as part of the North Field expansion project. This makes no economic sense.”

Diversifying options

Qatar is pivoting to become a larger trader of LNG in the meantime, and is handling more LNG outside of the Persian Gulf with the start of its Golden Pass export facility in the US. Shipments have started from the first train.

“We expect next year to have both the second and third trains in full operations. We are also building the largest ethane cracker in the world at the Golden Triangle Polymers Project.” The project will be starting up in the next few weeks, he said.

 “We will be, in the very near future, the largest LNG trader in the world by far,” said Al-Kaabi. “And we’re building our position to become the largest trader.”
The conflict in the Middle East is having a significant impact on mergers and acquisition. (Image source: Adobe Stock)

Global upstream mergers and acquisitions (M&A) activity is set to exceed last year’s US$175 billion total, with nearly US$130 billion in transactions announced as of August 2026 and a further US$137 billion in the pipeline, according to Rystad Energy

However, oil-price volatility is widening valuation expectations and making deal execution increasingly difficult.

Atul Raina, VP, oil and gas M&A said, “Oil price volatility has created a deeper opportunity set, but it has also made deals harder to execute. Sellers are looking at elevated spot prices and near-term cash flow, while buyers are underwriting against a backwardated price strip and the possibility that current conditions may not last.

"The opportunity is clearly there, but pipeline value does not automatically translate into executable deal value. Timing, transaction structure, and the willingness to bridge valuation expectations will determine whether the remainder of 2026 produces a breakout or a growing backlog."

Global upstream M&A deal value increased 55% year on year to approximately US$100 billion during the first half of 2026, with North America accounting for more than US$68 billion, or 68%, of first-half global deal value. Shale transactions represented more than US$63 billion—equivalent to 92% of North American activity and 63% of global upstream M&A. Devon Energy’s US$25.1 billion merger with Coterra Energy and Shell’s US$16.4 billion acquisition of ARC Resources together accounted for 41% of global deal value.

Middle East conflict expands the pipeline but slows down execution

The conflict in the Middle East has had a significant impact on upstream M&A. Approximately US$56 billion, or 56%, of first-half deal value was announced before the conflict began on 28 February. A further US$44 billion was announced from March through June, despite Brent averaging approximately US$99 per barrel between March and July. This is the lowest average monthly deal value since 2016 (US$10.7 billion monthly average) and 2020 (US$8.6 billion monthly average) when Brent prices averaged around US$44 per barrel around $42 per barrel, respectively.

At the same time, high but volatile prices have encouraged several E&Ps, particularly privately owned E&Ps in the US shale, to test the market, increasing the global opportunity pipeline from approximately US$98 billion before the conflict to US$137 billion currently. This volatility in prices and uncertainty around a potential resolution to the conflict also brings risks around deal execution. Rystad Energy expects buyers and sellers to respond with greater use of contingent or deferred considerations, flexible effective dates and stronger termination protections as buyers and sellers seek to share commodity-price and closing risk.

International dealmaking becomes more selective

Outside North America, first-half deal value increased 7% year on year to more than US$32 billion. South America led international activity with approximately US$13 billion, supported by consolidation in Argentina’s Vaca Muerta. Africa also recorded stronger activity as majors returned as buyers of offshore exploration positions in Angola and Namibia.

International activity is expected to remain more selective despite nearly US$52 billion of opportunities on the market. Major-led divestments and farm-downs will likely dominate as companies recycle capital, share development expenditure and reduce portfolio concentration while retaining exposure to strategically important assets.

The global M&A market therefore has sufficient opportunity depth to produce another strong year. However, it hinges on whether buyers and sellers can structure transactions that accommodate a volatile oil-price outlook and increasingly complex geopolitical risks.

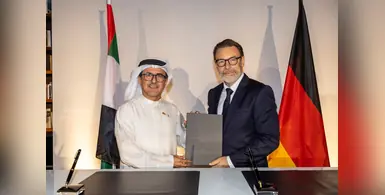
The signing between ADNOC and Bosch. (Image source: ADNOC)

ADNOC, XRG and Masdar have announced agreements with leading German companies, across energy, industry and advanced technology, potentially involving more than €5 billion of investment, combining the UAE’s expertise in energy and capital with Germany’s industrial and technological capabilities

The deals with RWE, Securing Energy for Europe (SEFE), MB Energy, Covestro, Siemens Energy, Siemens Industrial and Bosch Middle East span liquefied natural gas (LNG), gas, renewable energy, advanced materials and technology.

The agreements were signed during the state visit by UAE President His Highness Sheikh Mohamed bin Zayed Al Nahyan to the Federal Republic of Germany, when €40 billion in long-term investment in Germany was announced.

The agreements signed by ADNOC, XRG and Masdar include:
• ADNOC and RWE Supply & Trading GmbH Letter of Intent to progress LNG deliveries into Germany and Europe as well as Asia, supplied from ADNOC Gas’ and XRG’s growing LNG portfolio including Ruwais, Das, Rio Grande, Mozambique and Argentina, with supply commencing in the early 2030s.
• TA’ZIZ and Covestro are looking to progress a world-scale methylene diphenyl diisocyanate (MDI) value chain in Ruwais
• ADNOC, XRG and SEFE signed an agreement to explore cooperation in natural gas and LNG, spanning gas supply, infrastructure, logistics and portfolio optimisation, to support long-term energy security and market development in Europe.
• Covestro, Fertiglobe and MB Energy signed an MoU to collaborate on the development of low-carbon ammonia supply chains into Germany.
• In renewables, Masdar and RWE signed an MoU to consider joint participation in future German offshore wind auctions, while Masdar and Luxcara established a strategic partnership to explore joint investments in offshore wind and battery storage projects in Germany and wider Europe.
• ADNOC also signed Strategic Collaboration Agreements with Bosch Middle East, Siemens Energy and Siemens Industrial to explore collaboration on advanced technology and artificial intelligence.

The agreements build on existing investments by ADNOC, XRG and Masdar across Germany’s energy and industrial base. ADNOC also has 1.6 million tonnes per annum (MTPA) of long-term LNG supply agreements into the German market.

His Excellency Dr. Sultan Ahmed Al Jaber, ADNOC managing director and group CEO, Executive chairman of XRG, and Chairman of Masdar, said, “The UAE and Germany are building on decades of trusted partnership to advance economic growth and shared prosperity for the long-term. The additional €40 billion of intended long-term investments announced this week, together with the agreements ADNOC, XRG and Masdar signed today with our German partners, build on our investments across Germany’s energy and industrial landscape and mark another step forward in greater cooperation that will create new opportunities for both countries.”

In an interview with Bloomberg TV, UAE Minister of Foreign Trade Thani Al Zeyoudi said the €40 billon investment is about “reaffirming the long standing relationship and historical partnership” between the two countries.

“The 40 billion is just the beginning,” Al Zeyoudi said. “We’re going to shop around for the big opportunities that are going to bring this relationship to the next level.”

The UAE and other Gulf states are increasingly looking to broaden defense ties beyond Washington, as the Iran war drags on with no end in sight.

“The conflict is something we’re dealing with,” Al Zeyoudi said. “We’re maneuvering around the challenges and the impacts of the geopolitics and the region.”

The UAE is hoping that, by diversifying its international partners, it can pave the way to securing vital supply chains and potentially attracting production of equipment locally to bypass any export constraints, Bloomberg notes.

The IEA does not expect a recovery in supplies from the Gulf until next year. (Image source: Adobe Stock)

The IEA has once again revised down its oil demand and supply forecasts, as the stalemate in resolving the conflict in the Middle East and renewed attacks in both the Gulf and the Red Sea’s Bab el-Mandeb choke point continue to disrupt oil flows

World oil supply is now projected to average 100.7mn bpd in 2026, down 5.7mn bpd y-o-y, compared with the 4.3mn bpd forecast by the IEA a month ago, with a normalisation of supplies from Middle East producers now not expected until 2027.

Global oil production fell by 1.6mn bpd to 100.1mn bpd in August, as more than 10mn bpd of Gulf output remained shut in. Global oil stocks fell by 3.1mn bpd in August, leaving inventories at their lowest levels since 2023. Tanker costs were also up sharply, reflecting rising security risks and strong demand for ships.

OPEC+ crude production declined by 1.5mn bpd to 33.1mn bpd in August, as losses in Saudi Arabia and Iran outweighed a 980,000 bpd gain from Iraq. However output from some non-OPEC+ producers grew, particularly from the Americas.

Flows through the Strait of Hormuz averaged only 7.6mn bpd in August, 13.1mn bpd below pre-war levels, with cumulative export losses from the waterway approaching 2.8bn barrels.

Saudi Arabia hard hit

Saudi Arabia was particularly hard hit, seeing crude supply falling 2.3mn bpd to 6mn bpd in August, the lowest level in more than three decades, after Houthi-linked attacks on vessels and refineries, while Iran-backed militias in Iraq attacked the Abqaiq processing complex with drone strikes. Saudi Arabia has recently announced that the East-West pipeline has been shut as a precautionary measure, following drone attacks launched from Iraq. It is not known how long it will be until it is operational again. This could lead to a further squeeze on supply, given that the Kingdom had been able to reroute oil exports through the pipeline, which has a 7mn bpd capacity, to avoid the Strait of Hormuz.

Crude oil prices surged in September to their highest level since May, touching US$110 a barrel as hopes for a diplomatic solution to the crisis faded amid renewed attacks. After settling back slightly prices rose again following the attack on the Saudi East-West pipeline. Refined products prices have risen even more sharply, with fuels such as diesel reaching record highs, as both the Middle East conflict and Russia/Ukraine war damages oil refineries. Net diesel and gasoil exports from the Gulf and Russia were 1.6mn barrels a day lower in August than before the Middle East conflict.

Falling oil demand

Oil demand is also falling more than expected, partly ⁠due to sharp losses of petrochemical feedstocks and refined product supplies as well as record fuel prices, particularly for diesel, which are forcing consumers to cut their usage.

World oil demand will drop by 2.5mn bpd this year, the IEA predicted, more than its previous forecast of a 1.6mn bpd decline. (This is in contrast to OPEC, which still expects world oil demand to grow this year by 380,000 bpd). China has seen the biggest reduction, with oil imports, refinery activity and product deliveries significantly reduced. Demand reductions have also risen elsewhere, particularly in the Middle East as petrochemical operations and aviation have been impacted. With supplies still constrained, and commercial inventory buffers rapidly depleting, further demand reductions may be required in the coming months to close the gap, the IEA says.

Both the IEA and OPEC expect demand to rise next year; the IEA forecasts demand to rise by 2.6mn bpd in 2027 while OPEC forecasts a rise of 2.36mn bpd.

"Inventories have so far played a crucial role in balancing the market," the IEA said.

"With buffers shrinking and the global refining system stretched to the limit, the need for progress in resolving the conflict in the Middle East – and the Russia-Ukraine war, which is now in its fifth year – is greater than ever to avoid further market tightening."

The new standard represents an important step towards optical modem interoperability for subsea systems. (Image source: SWiG)

Oil and gas industry network Subsea Wireless Group (SWiG) has released a new industry specification for free-space optical communications, providing a common protocol for modems from different manufacturers

SWiGoptical Level 1 defines a simple protocol to satisfy interoperability and interchangeability requirements for subsea free-space optical communication devices. It supports applications including, but not limited to, process control, equipment and process monitoring, diagnostics and maintenance, and data exchange and harvesting across autonomous underwater vehicles (AUVs) and other connected subsea systems.

Systems working together

SWiG, a joint industry project (JIP) managed by OTM Networks (part of R&D consultancy Sagentia Innovation), was established to enable vehicles, infrastructure and equipment from different suppliers to work together seamlessly. It has 27 members representing all parts of the supply chain, from major energy operators to subsea service providers and integrators to specialist instrumentation companies. Its objectives include:

• Promote interoperability between users of subsea wireless communications.
• Raise industry awareness and acceptance of subsea wireless communications.
• Identify areas (within subsea wireless communications) where open standards are needed, and develop them.
• Encourage the integration of subsea wireless communication technologies.
• Share best practices across the industry.
• Promote knowledge transfer across the industry.

Shreekant Mehta, senior vice president, Energy Sector at Sagentia Innovation, said SWiGoptical Level 1 represents an important step towards optical modem interoperability for subsea systems.

“SWiG’s goal is to create a common subsea ecosystem where devices from different manufacturers interact seamlessly,” Mehta explained. “As subsea communication technologies continue to mature, a collaborative approach to developing open standards supports cost management and provides a common framework, reducing deployment risk, simplifying integration and supporting scalability. Achieving interoperability across subsea operations is essential if the industry is to realise the full benefits of autonomy.”

The new specification builds on the earlier SWiGacoustic standard and is the latest in a family of complementary SWiG standards that also cover radio frequency (RF), inductive data and power and hybrid communications. SWiGoptical Level 1 is now available to the wider industry, with Level 2 and Level 3 specifications for higher-performance protocols already under development.

More Articles …