


In The Spotlight
ADIPEC 2026 has opened in Abu Dhabi, bringing together more than 40 ministers, alongside policymakers, regulators, global CEOs and decision-makers to advance the decisions, partnerships and investments needed to strengthen energy security and support long-term economic growth
Taking place from 2-5 November at the Abu Dhabi National Exhibition Centre (ADNEC), ADIPEC 2026 is set for its biggest exhibition to date, with a record 2,260 exhibiting companies, 16 halls fully booked, 30 country pavilions and more than 239,000 attendees expected from over 170 countries. Among the participants are 54 national and international oil and energy companies (NOCs, IOCs, NECs and IECs), including bp, TotalEnergies, Eni, Oxy, ExxonMobil, Chevron, NNPC and INPEX. Major technology and industrial companies including Siemens AG, IBM and Microsoft will also participate.
Held under the patronage of His Highness Sheikh Mohamed bin Zayed Al Nahyan, President of the UAE, and hosted by ADNOC, ADIPEC 2026 takes place at a critical time for the global energy industry. Rising energy demand, geopolitical shifts and growing infrastructure requirements are placing energy security, resilience and investment at the centre of global economic priorities.
Keynote address
Delivering a keynote address at the opening ceremony, His Excellency Dr Sultan Ahmed Al Jaber, UAE Minister of Industry and Advanced Technology and ADNOC managing director and Group CEO, set the direction for four days of strategic dialogue and commercial engagement.
He highlighted that energy security has shifted from a specialist topic to a critical concern for every industry and household. Global supply buffers have eroded, evidenced by the loss of nearly 1bn barrels from inventories due to disruptions in the Strait of Hormuz. In some markets, stocks of diesel are at their lowest seasonal level in 35 years, while others are facing a 600 billion cubic feet LNG supply gap.
“But supply is only half the story. The other half is delivery. Before the disruption, logistics were less than 5% of the cost of a barrel. Today, they are more than 30%. In short, energy security is not only measured at the point of production. It is now also measured at the point of delivery.”
Five key steps for energy resilience
Dr. Al Jaber outlined five steps the energy industry can take to reduce the impact of future shocks.
“First accessible supply. We need expanded strategic storage, larger stockpiles of products and flexible refining capacity closer to consumer markets.
“Second, routes to market. Supply only counts when it arrives. Infrastructure must be built before it is needed and enabled by advanced logistics.
“Third, operational intelligence. Moving from automation operations to intelligent energy systems that anticipate risk, optimise performance and drive down the cost of every barrel.
“Fourth, capital follows confidence. Policy must create it, finance must accelerate it and insurance must keep trade moving.
“Fifth, which is in my view the most important, is people. Because behind every barrel that arrives is a person who made sure it did. Systems don’t carry responsibility, people do.”
Dr. Al Jaber praised the UAE’s armed forces, Civil Defense, firefighters, first responders and ADNOC’s front line employees for their selfless service in testing times and also acknowledged regional and global partners in the energy community for their contribution to keeping energy flowing during this period.
Dr. Al Jaber paid tribute to the example set by His Highness Sheikh Mohamed bin Zayed Al Nahyan, President of the UAE, highlighting his leadership and the values of unity and belonging that underpin the country’s resilience.
“Talent stayed. Capital stayed. Investment kept coming and the economy kept moving. That is the UAE model, pressure-tested and proven by results.
“The UAE will always advocate for dialogue, active diplomacy and pursue political solutions that bring stability to markets, to energy flows and to the global economy.”
Reflecting on the UAE’s resilience during recent market disruptions, Dr. Al Jaber said, “We did not write our resilience playbook during this disruption. We wrote it years before. And at ADNOC, it did not make us immune, it made us prepared. Our leadership’s foresight in modernising ADNOC made the difference, from integrated trading, to investing in people, to world-class logistics, to XRG’s global portfolio in gas, chemicals and energy solutions.
“The evident result is our end-to-end AI-enabled operating model, built for a world of rising demand and delivering what customers need, when they need it, where they need it.”
AI initiatives
Dr Al Jaber announced a new agreement between ADNOC, OpenAI and G42 as an example of how strategic collaboration and advanced AI can help reshape the energy industry, to optimise energy production and meet rising global demand. This collaboration will make ADNOC the world’s first energy company to deploy OpenAI Frontier to create smarter, safer and more resilient energy systems.
“From the moment ChatGPT was born, the world has asked what energy can do for AI. And now, together, we will find out what AI can do for energy.”
Following on from this, the gathering was addressed by Sam Altman, CEO of OpenAI who noted that while the AI industry has long requested energy, AI can now repay the favour by optimising the energy sector, describing the current era as a “new renaissance” where AI enables humans to solve complex problems and innovate at scale.
He praised the UAE as “the most forward looking country in the world for AI adoption” and noted the partnership with G42 and ADNOC is an opportunity to apply frontier AI models to the hardest problems in the energy industry, suggesting companies should “dream bigger” regarding what is possible with current advanced AI models. He stressed however that humans must remain in control of the future, ensuring
AI serves as a tool for people rather than a replacement for human agency.
“This is a value that we intend to really go fight for.”
The report highlights the evolution of AI in the energy sector
AI investment and adoption are accelerating across the energy industry as leaders increasingly recognise the potential for it to strengthen energy reliability and resilience in the current volatile environment, according to the third annual Powering Possible report from ADNOC, XRG and Microsoft
The report, entitled Energy Resilience in the Intelligence Era, highlights a significant shift from AI ambition to implementation, with AI delivering growing financial returns as well as creating new infrastructure challenges.
Key findings
• AI becomes a top corporate priority: 62% of energy leaders now rank AI among their top two priorities, up from 42% in 2025, while 89% report increased investment over the past year
• AI investments begin to deliver returns: 63% expect returns on existing investments to cover or exceed costs, rising to 89% for future investments
• Energy demand creates new infrastructure challenges: 74% expect AI to increase energy consumption by 2030, yet only 52% are confident existing infrastructure can meet AI-driven electricity demand – unchanged from 2025. Grid modernisation and smart-grid technologies are the leading investment priority for supporting AI growth, cited by 67% of respondents, followed by energy storage at 42%.
• Importance of energy reliability rises as a measure of AI value: 39% identify supply stability and reliability as AI's most important contribution, up from 26% in 2025, reflecting the current supply volatility. While the share giving cost savings as AI's leading contribution fell from 19% to 13%.
• AI has the potential to accelerate sustainable energy production: 71% of energy leaders expect AI to increase the speed at which the energy sector becomes more sustainable, alongside growing expectations that AI can strengthen resilience, efficiency and the ability to meet rising energy demand. 57% of respondents identify the optimisation of power flows, dispatch and balancing as the area where AI could make the greatest contribution to the energy transition.
• AI moves into everyday operations: The share of organisations deploying integrated agentic AI workflows more than doubled from 15% to 33%, while 60% are piloting or deploying robotics in physical operations, from inspecting infrastructure to performing hazardous tasks.
His Excellency Dr. Sultan Ahmed Al Jaber, ADNOC managing director and Group CEO and executive chairman of XRG said: “AI is creating significant new opportunities for the energy industry to drive greater value, strengthen resilience and improve safety and reliability. At ADNOC, we are embedding AI, robotics and advanced technology across our operations to optimize every barrel, every molecule and every megawatt we produce. As AI scales, energy and technology must advance together.”
Brad Smith, vice chair and president, Microsoft, added, “As AI becomes embedded in the sectors that underpin the global economy, the measure of progress will not be adoption alone, but whether it delivers lasting value while earning public trust. In the energy sector, where reliability and security are fundamental, that requires strong governance, clear accountability and sustained investment in people and skills. Innovation at scale must be matched by responsibility at the same scale.”
The findings underline the need for investment in energy and digital infrastructure to advance together, backed by strong cybersecurity, trusted AI-ready data, common standards, sound governance and a skilled workforce, so AI can be deployed safely and reliably at scale.
Powering Possible 2026 is being published ahead of the fourth ENACT Majlis in Abu Dhabi and ADIPEC 2026 and is based on a survey of almost 400 senior energy and finance leaders.
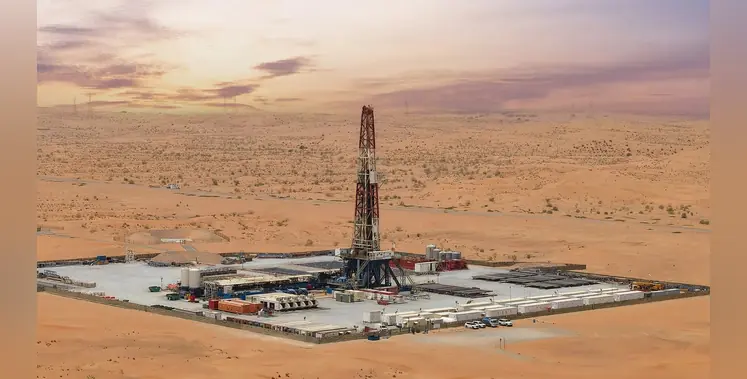
First gas was achieved within less than a year from discovery. (Image source: SNOC)
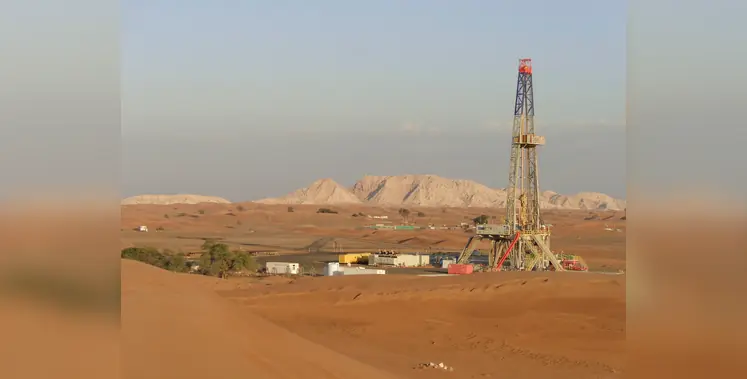
In a development that is set to strengthen Sharjah’s energy security and help the UAE achieve its goal of gas self-sufficiency by 2030, Sharjah National Oil Corporation (SNOC) has successfully completed Phase 1 development of the Hedebah gas-condensate field
Discovered in May 2024, the Hedebah Field represents Shrajah’s fifth onshore gas and condensate field and is located northeast of the Sajaa gas field. Thanks to an accelerated appraisal and development programme, first gas from the field was achieved within less than a year of discovery. SNOC has now completed all key Phase 1 objectives, including appraisal drilling, well evaluation, gathering infrastructure, pipeline installation and commissioning activities.
Appraisal results have confirmed strong reservoir quality, favourable pressure characteristics and encouraging production performance across the field, increasing confidence in Hedebah’s long-term commercial potential and its future contribution to Sharjah’s energy needs. The field has already more than doubled the company’s current gas production, ensuring a steady supply of gas and condensate.
SNOC has already commenced preparations for the next stage of development, with activities being accelerated to ramp up production during 2027. The field is expected to reach plateau production by 2028 and make a substantial contribution to meeting future energy demand across the Emirate.
The project was delivered despite significant logistical and procurement challenges, including regional shipping disruptions and material supply constraints, demonstrating SNOC’s ability to execute complex developments on an accelerated timeline.
Khamis Al Mazrouei, CEO of SNOC, said, “Hedebah is one of the most significant gas developments in Sharjah in recent years and a cornerstone of SNOC’s long-term growth strategy. Completing Phase 1 and bringing the field into production demonstrates our ability to move quickly from discovery to delivery while supporting the Emirate’s growing energy requirements. As we move into the next phase of development, Hedebah will play an increasingly important role in strengthening energy security and creating long-term value for Sharjah.”
SNOC remains committed to advancing Sharjah’s energy independence through the exploration and development of its hydrocarbon resources, complemented by its strategic gas storage and processing infrastructure.
Contributing to UAE gas growth
The SNOC development is good news for the UAE's strategic gas growth plans. The UAE possesses 297 trillion cubic feet (Tcf) of conventional natural gas reserves, ranking as the seventh-largest gas reserve holder globally. Major projects are underway to exploit these to secure domestic self-sufficiency, help meet rising global gas demand, provide critical feedstock for the nation’s growing industrial and petrochemical sectors and establish the UAE as a global gas and LNG player.
They include:
Umm Shaif Gas Cap Megaproject: ADNOC’s US$6.2bn project in partnership with TotalEnergies, Eni and CNPC will unlock more than 600 million standard cubic feet per day (scfd) of natural gas and associated gas liquids by 2030, equivalent to almost 10% of the UAE’s current daily gas consumption
ADNOC Gas Rich Gas Development (RGD) project: With a total investment value of US$13.2bn across three phases, the RGD project is expanding the company’s gas processing capacity. Phase 1 expands key processing units to increase throughput and improve operational efficiency across multiple gas assets; Phase 2 will add a new natural gas processing train at the Habshan facility, while Phase 3 will add a new natural gas liquids (NGL) fractionation train at Ruwais.
Ruwais LNG project: This is scheduled to start operations in 2028, adding 9.6 mtpa of LNG production capacity, more than doubling ADNOC’s LNG production output to around 15 mtpa. Supported by ADNOC and XRG’s integrated global LNG ma
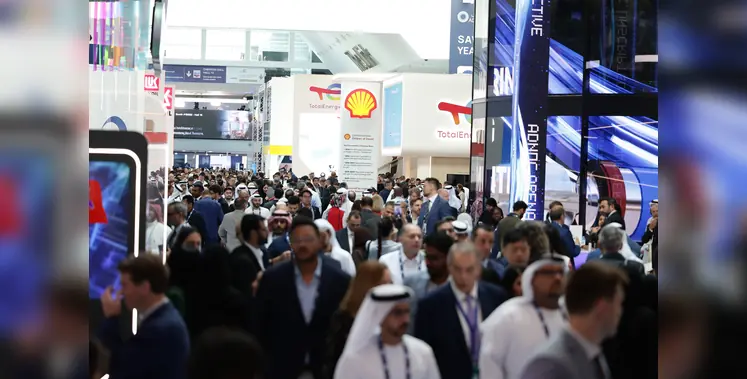
ADIPEC 2026 will feature more than 2,250 exhibiting companies. (Image source: dmg events)
In an exclusive interview with Oil Review Middle East, Thomas Löffler, executive vice president, dmg events discusses what we can expect at ADIPEC this year
Oil Review Middle East: At this time of geopolitical volatility, rising energy demand and infrastructure constraints, how will ADIPEC help to advance the investments, projects and partnerships required to support the delivery of secure, reliable and affordable energy systems?
Thomas Löffler: The last few months have reinforced something important: the energy system that was carefully built over decades is no longer the system the world now needs. We need a system that can absorb shocks, adapt to changing conditions and continue delivering the energy required for long-term economic and societal progress. That is why energy security is economic stability, and resilience has become fundamental to both.
The imperative is now twofold: secure the energy the world relies on today, while investing in the infrastructure, technology and capabilities needed to expand capacity and strengthen resilience for the future. That requires significant capital, faster execution and much closer collaboration across sectors and borders.
ADIPEC 2026 is where those priorities come together. Across the Strategic and Technical Conferences, Leadership Roundtables and the exhibition, we bring together governments, energy producers, investors, technology companies, engineers, manufacturers, infrastructure providers and major energy consumers to address the practical questions that determine delivery: where capital needs to go, what makes projects bankable, how infrastructure can be built faster and how technology can move from pilot to scale.
Collaboration is critical because no single company, country or sector can deliver the next energy system alone. ADIPEC brings together the full breadth of the global energy industry, from every part of the world, creating the conditions for ideas to become decisions, partnerships to become projects and investment to translate into real-world capacity. As a global centre for energy, investment and technology, Abu Dhabi and the UAE are uniquely positioned to convene those conversations and help accelerate progress.
Given the convergence of rising energy demand, AI-driven power growth, infrastructure constraints and geopolitical volatility, this is one of the most important editions of ADIPEC in recent years. The focus is not simply on discussing the challenges facing the industry, but on strengthening supply, mobilising capital, accelerating technology deployment and advancing the partnerships needed to build a more resilient energy system for the future.
Oil Review Middle East: What will be the key themes and topics at ADIPEC this year, and how has the strategic conference been refreshed to reflect changing priorities?
Thomas Löffler: The Strategic Conference has been significantly refreshed this year to reflect the issues now determining how the global energy system develops and performs. At its core are three priorities: strengthening energy security and resilience; mobilising the capital and infrastructure required to meet rising demand; and embedding intelligence and technology across energy systems to improve performance, reliability and decision-making.
New programmes include Energy Security & Resilience; Policy, Regulation & Governance; Upstream; Clean Power, Molecules & Carbon Management; Grids, Infrastructure & Industrial Execution; and Workforce & Skills, alongside updated programmes focused on AI, digital technology and integrated industrial value chains.
These changes reflect how interconnected the industry has become. Energy security cannot be separated from infrastructure and investment. AI is both changing how energy systems operate and creating significant new demand for power. And delivering projects at the scale required will depend as much on regulation, workforce capability and partnerships as it does on technology.
There is also a much stronger emphasis on execution. The conversation is no longer simply about long-term ambition. It is about what makes projects investable, how capital moves into infrastructure, how technology gets deployed at scale and how partnerships accelerate delivery.
Ultimately, the programme is built around the decisions the industry needs to make now — where to invest, what to build, which technologies to scale and how to deliver the capacity the world will need.
Oil Review Middle East: What is the role of the ADIPEC exhibition and its specialised zones in showcasing the latest innovations and technologies and catalysing commercial partnerships?
Thomas Löffler: The exhibition is where a lot of the commercial activity at ADIPEC happens. More than 2,250 companies come together not simply to showcase technology, but to meet customers, identify project opportunities, build partnerships and move solutions closer to deployment.
Across 16 halls, 30 country pavilions and four specialised zones, the exhibition connects energy companies, technology providers, manufacturers, service companies, investors and project partners in one commercial environment.
The AI Zone shows how AI, robotics, automation and advanced analytics are moving from pilot to real-world deployment across energy assets and operations, while the Digitalisation Zone focuses on the digital infrastructure, automation, analytics and cybersecurity capabilities making energy systems more connected, responsive and resilient.
The Low Carbon & Chemicals Zone brings together technologies and commercial models spanning carbon management, lower-carbon solutions, chemicals and advanced materials; and the Maritime & Logistics Zone focuses on the shipping, ports, supply chains and infrastructure required to keep global energy flows secure, efficient and reliable.
These zones play an important role in bringing operators, technology companies, project owners and investors into the same environment. That is where technology moves from being demonstrated to being evaluated, financed and deployed.
Oil Review Middle East: With the rapid expansion of AI and the transition from pilot projects to large-scale deployments, and as AI safety concerns come to the fore, how will ADIPEC shape the effective and responsible deployment of AI and intelligent energy systems?
Thomas Löffler: As AI moves into mission-critical energy infrastructure, the focus must extend beyond capability to include governance, transparency, cybersecurity and human oversight. ADIPEC will bring together operators, technology providers and policymakers to ensure AI is deployed safely, responsibly and at scale.
The AI Zone will show how artificial intelligence, robotics, automation and advanced analytics are moving from pilot to real-world deployment across energy assets and operations. At the same time, the AI, Digital & Technology conference programme will bring energy and technology leaders together to examine how these technologies can improve performance, strengthen resilience and support increasingly complex energy systems.
That depth extends across ADIPEC. Some of the world’s most influential energy and technology leaders will be part of the conversation this year, including Dr Roland Busch, President & CEO, Siemens AG; Olivier Blum, CEO, Schneider Electric; Caspar Herzberg, CEO, AVEVA; Girish Rishi, CEO, Cognite; Dennis Jol, CEO, AIQ; Uljan Sharka, Founder and CEO, Domyn; Dr Olivier Oullier, CEO, Inclusive Brains; and Tim Bawtree, Chairman and Founder, Quantum Switch.
Bringing that level of leadership together with more than 2,250 exhibiting companies, investors, project owners, engineers and technology providers is what creates the opportunity for ideas to move into partnerships, investment and deployment.
The point is not scale for scale’s sake. It is what that scale enables: bringing the people developing technology together with the companies that need it, the investors that can finance it and the decision-makers who can take it to market.
Sherif Foda, CEO, NESR. (Image source: NESR)
NESR’s strong local presence as a national home-grown energy services provider has enabled it to weather the challenges posed by the current crisis in the Middle East, while others have floundered
Speaking to Oil Review Middle East at the Energy Intelligence Forum in London, where energy security and energy resilience were at the top of the agenda, NESR’s CEO Sherif Foda explained how right at the beginning of hostilities the company had put plans into action through its crisis management team to ensure business continuity and prepare for any possible disruption.
“What helped us a lot is that we have built a very strong and competent local workforce so we don’t need to rely on expatriates to come in to execute the jobs. The other aspect is to ensure you have the products you need to operate. We shipped everything we needed immediately, in some cases taking a conscious decision to air freight or incur more costs to be able to have ready equipment, people and products in country in case of conflict. So we actually grew during the conflict despite those challenges.
Foda cited the Jafurah unconventional gas project in Saudi Arabia as a case illustrating supply chain resilience.
“We worked with our technology partners and suppliers to ensure we can blend the surfactants in country, for example. We have sourced most of our needs locally, such as the pipes, infrastructure, and sand, with some of the products made in Saudi Arabia. As a result of that resilience, we continued with our frac performance in unconventional without disruption, and are marching ahead as we speak and into the coming months. No one would have believed 10 years ago that Saudi Arabia would have a competitive play that rivals the Permian or Delaware. Today it is second to none, a world-class unconventional play, developed with the latest technology and 100% local crew. So there has been no need to evacuate workers, giving us a competitive advantage.
“So we are growing our projects despite what’s happening in the region.” Indeed, NESR saw second quarter revenues grow 59% year on year, with a tripling of net income, as the company was able to execute all its contracts and maintain a presence in all operating units, with no interruption to any of its customer activities.
Logistics has been the biggest hurdle posed by the crisis by far, Foda said. “Logistics has been very, very complex. We planned the logistics at an early stage, deciding to truck goods from Jeddah to Dammam rather than going through the Strait, at considerable cost.”
Opportunities throughout the region
Discussing the company’s growth plans, Foda said he sees strong opportunities throughout the region.
“We see fantastic growth in the UAE and Kuwait, and we’ve been increasing our footprint and business in Saudi Arabia,” he says. In Kuwait, NESR in August announced multiple contracts totalling US$300mn over five years, including an agreement to establish a research centre that will focus on several challenge-specific innovations in multiple disciplines across upstream, sustainability, and unconventional resources. NESR will pioneer innovation and bring best-in-class technologies from around the world, tailoring them to the upstream ecosystem in Kuwait. While back in March the company announced it had secured US$300mn worth of cementing contracts in Kuwait and North Africa.
“North Africa has enormous potential because of its gas, offering the scope to replace Russian gas supplies to Europe,” Foda says. “Then you have what they call the new frontier – Syria has come back, Iraq post-conflict will offer a lot of opportunity.
“That is why the region offers so much, and it’s a very unique opportunity for a company like us, because you need to be very locally established. The current situation has shown that is cost prohibitive to employ expatriates, who come and go. You have to be locally made, homegrown, while conforming to or surpassing the top international standards.”
Others should be building local capacity, as NESR is, he said, while conceding that certain products will still need to be imported or locally assembled. “You’re not going to be able to build a high-pressure wellhead in every country. It won’t be cost competitive. But for the products that are used a lot, the main components of those items should be sourced locally. The local structure also has to be done extremely well.”
Decarbonisation technology potential
NESR has always had a strong ESG focus. Discussing decarbonisisation, Foda said this is not seen as the flavour of the day right now due not only to the conflict but also due to the stance of the US administration.
“But it will come back; it is a must. We cannot as an industry continue to produce oil and gas with the same level of emissions, especially as demand is increasing. We need to eliminate emissions as far as possible. ESG is a good business path. And as the CEO of Aramco has said, this region produces oil and gas at the lowest cost with the lowest emissions. That means projects will happen.” He added that now is a good time to invest counter-cyclically in ESG and decarbonisation technology, as NESR is doing, as there are companies with very good technologies that are currently available at a low cost due to lack of demand. “It is a very good opportunity to invest and make acquisitions to get ready with your portfolio of decarbonisation implementation technology.”
NESR is spearheading environmental innovation on multiple fronts, deploying technologies across water management, flare elimination, emissions detection, heat capture, and energy transition (CCUS & Hydrogen) and now pushing into minerals for the energy transition, recently signing an agreement with Aramco for the region’s first direct lithium extraction (DLE) project.
Foda sees the greatest potential for technology breakthrough in decarbonisation, in particular addressing the economics of decarbonisation. For example if recycling produced water were made economically viable, it would be much more widely practiced. “We need to break through the economics of materials, for example DLE technology to extract lithium,” he said.
At ADIPEC, NESR will be focusing on unconventional development and minerals, such as rare earth minerals. “We have a very cool technology we want to present at ADIPEC,” Foda said. Watch this space!
Concluding, Foda declared himself “super positive” about the future, seeing “the post-conflict box of opportunity”.
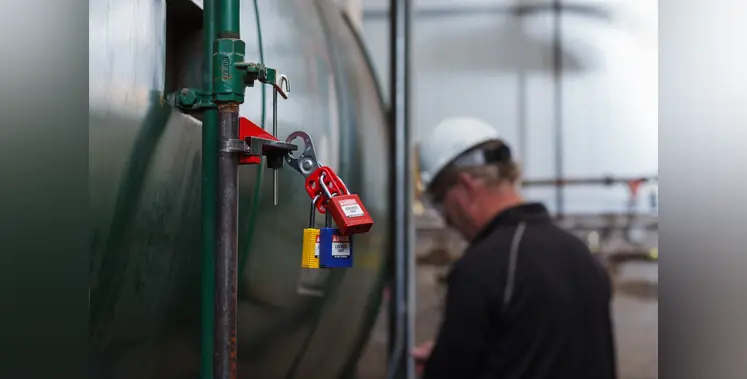
The recent European Norm 17975 addresses ‘grey zone’ energy-related risks during machine and pipeline interventions and proposes a task based framework for safe and efficient work. The norm can further increase the safety and efficiency of Lockout/Tagout programmes in a wide range of industries
A task based safety framework
10%-15% of fatal workplace accidents in Europe’s industries are related to maintenance operations according to data from the European Agency for Safety and Health at Work. Many of these result from underestimating risks involved in specific tasks such as machine greasing, sensor adjustment or a quick cleaning that are not always seen as ‘maintenance activities’. They are kept outside the scope of Lockout/Tagout programmes even though workers are exposed to similar risks. European Norm (EN) 17975 addresses these grey zone risks by using task based risk analyses as a starting point.
“EN 17975 does not require an energy zero state for every machine or pipeline during every intervention”, said Mustafa Ekseri, EMEA Safety Engineer at Brady Corporation, a supplier of quality Lockout/Tagout solutions.
“Not having to halt an entire production line for every intervention can save valuable time - if it is possible in a safe way. To achieve this, EN 17975 proposes a layered approach based on risks related to specific tasks on specific machines and pipes. These risks are to be highlighted in a risk analysis. In absence of a risk analysis, machine zero energy states remain the safety standard. In that sense, EN 17975 builds on ISO 14118 by providing more options for compliance with European workplace safety legislation. Impacted activities can be defined using EN 17007 and EN 13306 and are also listed in EN 17975.”
Risk analysis guidance
With machine and pipe intervention safety hinging on identified risks, industries will need thorough task-based risk analyses. Guidance can be found in other standards. “ISO 12100, primarily intended for machinebuilders to take into account their customers’ workplace safety, can be used as a basis for machine intervention risk analyses. ISO 31000 provides guidelines for managing risk in general, including 8 core principles, a framework and a process.”
“EN 17975 proposes 6 steps to analyse the risk in any machine intervention task, starting with the identification of the task, all the way to a feedback loop for continuous improvement. That includes a thorough energy source inventory and identification. The standard also requires a risk analysis update before applying Standard Operating Procedures, and during maintenance activities. In addition, EN 17975 advocates clearly identified degraded situations that may deviate from the standard risk assessment.”
Task-based isolation
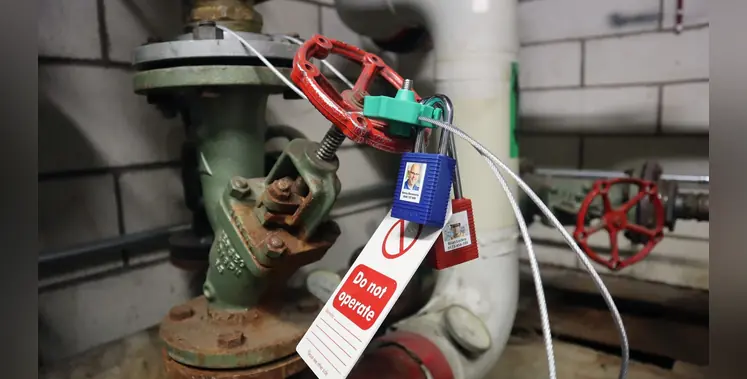 EN 17975 uses a task based risk approach that was captured earlier in the French norm X60-400. Based on a task risk analysis, the European Norm proposes four types of risk control processes:
- Neutralisation: a process that, through design of the control systems, shuts down an item of equipment so that a list of predetermined tasks can be conducted in safety.
- Standard isolation: a process that results in the removal – by locking in position a single or double isolating device – of all energies & fluids where the presence, accidental retention, unexpected appearance does not have hazardous consequences for workers, the environment, and items.
- Reinforced isolation: a process that results in the removal – by separation or by a combination of isolating and opening devices (e.g. valve, tap, etc.) – of all energies & fluids where the presence, accidental retention, unintended appearance does not have hazardous consequences for workers, the environment, and items.
- Specific provisions: a process that results in the implementation of organisational or technical measures enabling observation, diagnostics, testing activities and work on settings for the item in service to be carried out safely, with energies & fluids present.
“All four risk control processes require an inventory of energies and fluids per machine with their effects on people, property and the environment, a mapping of the isolating devices and an identification sheet of energies, fluids, components and lockout devices. It also requires a shared risk assessment grid and process. EN 17975 describes the aim, application conditions, type of activities and other relevant factors for each of the 4 risk control processes.”
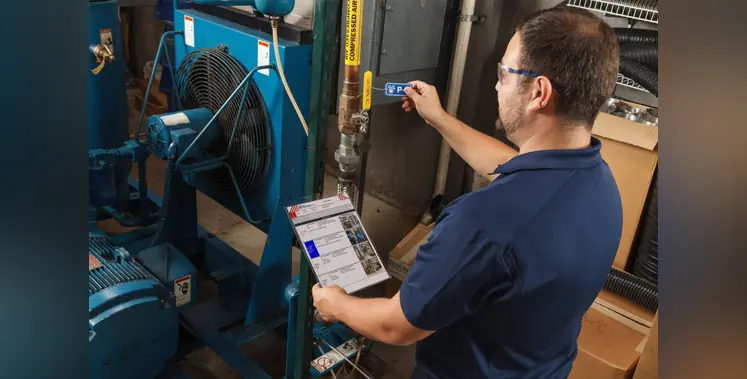
Lockout/Tagout guidance
Complying with EN 17975 requires a human, organisational and technical approach, all of which are outlined in the norm.
EN 17975 identifies 9 steps to carry out reinforced and standard isolations by Lockout/Tagout of energies and fluids. Steps involve separation of energies and fluids, isolation, lock out, tagout, identification, dispersion of energies, check, contain and inspect. “The ‘check’ step in EN17975 is already widely known in the industry as the ‘Tryout’ in Lockout/Tagout/Tryout or LoToTo. It is a vital step to help make sure that measures are implemented correctly and that they are still effective.”
“Brady safety engineers can help industries implement isolations by writing machine- and task specific lockout procedures. These can include all nine steps from EN 17975, and they must be based on company task risk assessments. In addition, we can offer the right Lockout/Tagout tools for procedure compliance, set up a hands-on demo by locking out a specific machine, and provide training to relevant employees. Alternatively, a gap analysis can be made that identifies steps to be taken from the current state to arrive at compliant, best practice Lockout/Tagout.”
Impact on existing safety programmes
EN 17975 is not a legal requirement. “The standard however considerably facilitates compliance with EU workplace safety legislation. It sets a clear expectation for any machine intervention: if no risk analysis for the task is available, a machine zero energy state is required.”
“Because many safety programmes already involve complete machine isolation from every energy source, for every task, it is likely that the new norm will impact existing Lockout/Tagout-programmes. Based on the risk analysis, machine zero energy states may not be needed for every type of intervention.”
“Adversely, some tasks that were considered ‘small and safe’ may unveil more risk after a thorough risk analysis. This means a single machine could have several Lockout/Tagout procedures. The right procedure can be included with, or communicated via a QR-code on a work permit for example.”
“Some forms of automated safety may not be sufficient for every task without an underlying risk analysis. Take a safety cage for example, equipped with sensors that deactivate moving machine parts the moment someone enters the cage. Do these nullify any residual energy that may pose a risk? Is gravitational, and other potential energy taken into account? The goal of EN 17975 is to prevent accidents, and to avoid a false sense of safety that does not provide any real protection.”
With the European Norm 17975, industries in Europe can now rely on a common standard for compliance with EU and national safety legislation that involve risk control processes of energies and fluids in maintenance activities.
Get the Brady EN 17975 Lockout/Tagout webinar recording
Go from zero machine energy to zero intervention risk with task based Lockout/Tagout, driven by the European Norm 17975. Get your copy of the EN 17975 webinar from an experienced, worldwide Lockout/Tagout solution provider.
Discover more about:
- the unique European framework EN 17975 provides to achieve safety and efficiency
- how EN 17975 focuses on task-based safety, rather than machine zero energy states
- how EN 17975 can be used to address ‘Grey zone’ risks
- Four risk-based energy isolation levels presented by EN 17975
- Six steps to control risks
- Lockout/Tagout procedure writing
- Lockout/Tagout device and padlock types
Get the webinar recording now >
Draw inspiration from our free guidebook on how to best implement Lockout/Tagout. . Download the free guide >
BRADY Middle East
 Mustafa Ekseri works as a Safety Engineer for Brady Europe, Middle East and Africa. He is involved in planning, writing procedures and rolling out Lockout/Tagout programmes at manufacturing and logistics workplaces throughout Europe. He is a Prevention Advisor Level 2, a Belgian legally regulated curriculum that equips professionals to handle safety and health risks in businesses.
Nayef Bou Chaaya, vice president, Middle East, Turkey & Central Asia, AVEVA.
The Strait of Hormuz crisis shows how vulnerable the supply chain is to geopolitics, making agility and resilience impossible to ignore, writes Nayef Bou Chaaya, vice president, Middle East, Turkey & Central Asia at AVEVA
The oil industry began the year determined to boost crude production to cover a looming global supply-demand gap. Yet on February 28, that challenge became far more acute than anyone could have predicted.
The onset of the US-Israel-Iran war and the ensuing Strait of Hormuz crisis has completely changed the mood inside the oil industry. The world is facing prolonged higher-for-longer oil prices where every barrel suddenly matters more, and every operational inefficiency starts eating directly into profits.
At the peak of the disruption, the market was dealing with the loss of around 12 million barrels per day of crude supply, according to Rystad Energy. That is roughly 11% of total global oil demand. On an annualized basis, it equates to more than four billion barrels of supply either trapped, delayed or prevented from reaching the market efficiently.
Oil prices had jumped from around USUS$80 per barrel before the conflict to above US$100. Some analysts project prices could still edge to $180 by the end of the year. That has created a rare profit window for producers outside the Middle East, who are trying to strike while the iron is hot and get as much as possible out of existing infrastructure while conditions remain favourable.
This is not just about drilling more wells
As time is of the essence – both for countries keen to get more supply and for oil majors who want to make the most of high prices – the focus is now on optimising every drop.
Small improvements in uptime, throughput or refinery performance that might once have had limited commercial impact can now translate into millions of dollars in additional revenue. A compressor failure or unplanned shutdown that was once a routine maintenance headache is now enormously costly.
This is where predictive analytics can have an outsized impact, enabling producers to constantly monitor assets and catch problems before they escalate into equipment failure or shutdowns. The current geopolitical environment has only turbocharged this shift, accelerating the move towards industrial AI and integrated operational systems across the sector.
Rystad Energy estimates AI and digital technologies will create close to US$500 billion in cumulative value for exploration and production (E&P) companies between 2026 and 2030.
Not all crude is equal
Refiners are also dealing with another major challenge: crude availability has become much more unpredictable.
Refineries use blends and slates sourced from multiple regions, which all have different properties and refining characteristics. Texas crude behaves differently from Saudi crude. Saudi crude behaves differently from Abu Dhabi crude. Venezuelan crude behaves differently again.
In stable market conditions, those crude slates are relatively predictable. However, refiners are now forced to change their crude oil slate because certain crude streams are no longer accessible. This creates a much more complicated optimisation problem.
Historically, engineering teams would run a limited number of operational scenarios manually. Now industrial AI systems can run thousands of crude blend combinations simultaneously while incorporating crude prices, refined product prices, electricity costs, operational constraints and regional market demand – determining in near real-time exactly which combination will generate the highest profitability possible.
AI augments human strategy
Importantly, the industry is not treating AI as some magical black box replacing engineering expertise. Inside oil and gas, there is still a very strong understanding that AI is only as good as the underlying engineering models feeding it.
AI is extremely good at interpreting data, however, the actual engineering calculations still need to come from first-principles engineering models and thermodynamics.
I like to use a comparative aviation analogy. For example, let’s say passengers boarded a plane and someone announced that AI would be flying the entire flight. Most people would probably get off right away.
Yet, modern aviation already relies heavily on automation. Pilots still handle take-off, landing, direction, speed and oversight while automated systems manage most of the journey in between. Industrial AI is evolving in a similar manner.
Human operators still define objectives, constraints and desired outcomes while AI handles huge amounts of analytical work and scenario modelling faster than humans can manually. This practice matters in a conservative industry where operational mistakes carry enormous financial and safety consequences.
Counting the cost
Production accounting systems are also becoming strategically more important because relatively small discrepancies in incoming or outgoing shipments can seriously affect margins when oil prices are high. If a company purchases one million barrels but only receives 990,000, the financial implications suddenly become much more significant.
In sum, what this all means is that the market is increasingly rewarding operational integration as much as production scale.
While longer term, the industry will continue investing in energy diversification, right now the challenge is more immediate: keeping the world moving during one of the most volatile commodity environments in decades – and making every barrel count.
No one knows when this window will close – or when the next one will open.

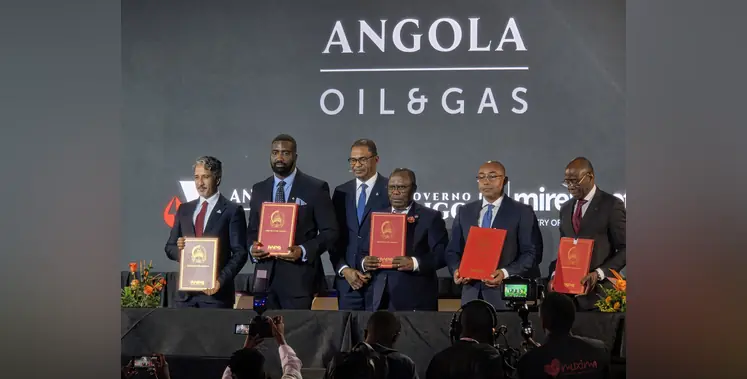
The agreement signing. (Image source: QatarEnergy)
QatarEnergy, with its partners Shell and Sonangol E&P has signed an agreement with Angola’s National Agency for Oil, Gas, and Biofuels (ANPG) to hold interests in Blocks 8 and 22 offshore the Republic of Angola
Under the agreement, and subject to the relevant governmental approvals and final contractual arrangements, QatarEnergy will hold a 30% working interest, while Shell (the operator) will hold 50%, and Sonangol will hold 20% in the two offshore blocks.
For QatarEnergy, the agreement marks another important step in advancing its ambitious international exploration strategy, with maximising value from upstream being one of its five key strategic pillars in its vision to be one of the best energy companies in the world.
QatarEnergy acquired a 40% stake in the North Rafah block, offshore Egypt in October 2025, following hard on the heels of the acquisition of a 27% participating interest in the North Cleopatra block offshore Egypt, operated by Shell. QatarEnergy has also acquired exploration licences in the Republic of Congo, Algeria and Namibia.
His Excellency Saad Sherida Al-Kaabi, the Minister of State for Energy Affairs, the president and CEO of QatarEnergy, said: “QatarEnergy is pleased to sign this agreement and to establish a presence in the energy sector of the Republic of Angola as part of our international upstream exploration strategy and growth efforts. We would like to thank the Angolan authorities, and our partners Shell and Sonangol, for their cooperation and support. We look forward to a longstanding and fruitful partnership.”
The agreement was signed in the Angolan capital Luanda on the sidelines of the Angola Oil & Gas Conference, where the Minister of Mineral Resources, Petroleum and Gas, Diamantino Azevedo, highlighted the contribution of oil activity to the diversification of the economy and outlined the main lines of the Executive's vision for the sector.
ANPG formalised a series of offshore entries, risk-service contracts and other agreements with international oil companies at the show, advancing exploration across the Kwanza and Congo Basins.
Sonangol presentations emphasised the national oil company's contribution to boosting the market, attracting capital, and consolidating strategic partnerships.
The collaboration will define a framework for providing subsurface data across Morocco's onshore and offshore basins. (Image source: Adobe Stock)
Studies indicate total recoverable resources of up to 43mn barrels of oil. (Image source: Adobe Stock)
Around half of oil and gas producers identify Asia Pacific and the Middle East among their most important customer regions over the next five years. (Image source: Adobe Stock)
The Middle East is identified as the region offering the greatest opportunity over the next decade despite the current instability, according to the inaugural ADIPEC Global Energy Report 2026: Power Shift report, based on surveys of more than 1,800 senior business and energy leaders
Energy’s centre of gravity shifts east
72% of respondents expect the Middle East to become more important in global energy, with around half of oil and gas producers identifying Asia Pacific and the Middle East among their most important customer regions over the next five years, highlighting the growing commercial importance of the Gulf-Asia corridor.
Confidence in the global energy industry's future remains strong despite ongoing uncertainty, with 85% of energy insiders saying the sector is more attractive to invest in than five years ago. Nearly two-thirds of senior industry leaders, 64%, say the global energy system proved more resilient than expected through recent disruption, pointing to the energy sector’s ability to adjust quickly to shocks while 77% remain optimistic about the decade ahead.
AI reshapes demand and influence
Artificial intelligence is expected not only to create a new source of pressure and opportunity, but also to reshape who holds influence in the energy system. More than four in five energy insiders expect AI-driven electricity demand to exceed current forecasts, including 32% who expect it to be much higher.
At the same time, 71% see AI as more of an opportunity than a risk, while 43% expect technology and AI companies to gain the most influence over global energy during the coming decade, ahead of governments and regulators, financial institutions and traditional energy companies.
From resilience to execution
The combination of growing demand, strong investment appetite and technological change shifts the challenge for the industry from resilience towards execution.
The research clearly shows broad agreement that future demand will require a diversified response: 93% say meeting future energy demand will require growth across multiple energy sources rather than reliance on one dominant source, the strongest consensus identified in the research.
Infrastructure is emerging as a critical constraint. Delays in building and connecting grids are identified as one of the biggest barriers to meeting future demand after geopolitics, and the research identifies greater grid investment as a priority. At the same time, 74% expect the Middle East to play a more significant role in building energy infrastructure over the coming decade.
The findings will help frame discussions at ADIPEC 2026, where leaders will examine how to mobilise capital, accelerate infrastructure development and strengthen the partnerships needed to meet rising global demand.
Christopher Hudson, president of dmg events, the organisers of ADIPEC, said, “What stands out from this research is that confidence has held up despite a period of disruption. Energy demand continues to grow, the Middle East and Asia are increasingly central to that growth, and AI is reshaping what the industry needs to deliver.
“But confidence alone alone won't meet that demand. We need investment to move into projects, infrastructure to be built and new partnerships to take shape. The report gives us a clear picture of the priorities. ADIPEC is where the industry comes together to make decisions and move them forward.”
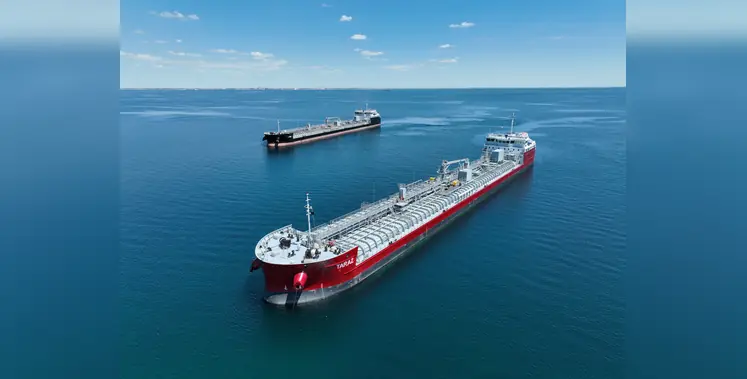
Tanker shipping is fundamental to global energy trade. (Image source: Noatum Maritime))
First gas was achieved within less than a year from discovery. (Image source: SNOC)
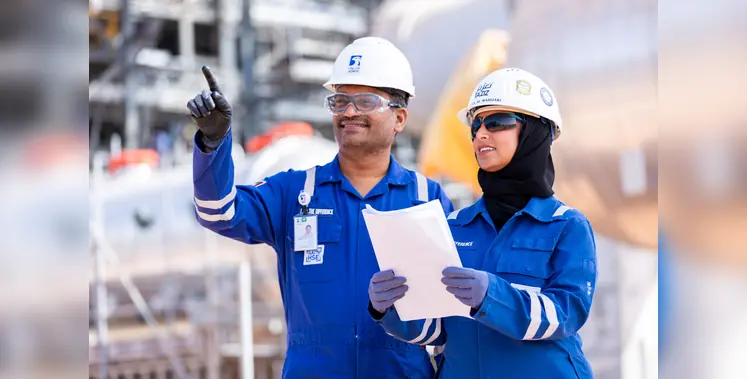
The agreements will expand the chemicals ecosystem. (Image source: ADNOC)
TA’ZIZ, a joint venture between ADNOC and ADQ, has signed long-term agreements spanning offtake, feedstock and sales across its chemicals portfolio, valued at US$28.5bn (AED104.6bn)
Signed at the Make it in the Emirates Forum, the agreements, valued at US$28.5bn, secure both global offtake and reliable local feedstocks, allowing for large-scale chemical production within the UAE and reinforcing TA’ZIZ’s role in building a fully integrated domestic chemicals ecosystem. The deals include sale agreements with ADNOC and Proman for methanol; Emirates Global Aluminium (EGA) for caustic soda; Mitsubishi Corporation for ethylene dichloride (EDC), vinyl chloride monomer (VCM) and caustic soda; Mitsui & Co. for EDC and caustic soda; Sanmar Group for EDC and VCM; Tricon for PVC, EDC and caustic soda; and Vinmar for EDC and polyvinyl chloride (PVC).
ADNOC Gas secured a 25-year feedstock agreement to supply natural gas to the TA'ZIZ methanol project valued at over $5 billion (AED18.4 billion). TA’ZIZ also agreed a 20 year salt supply agreement with Abu Dhabi based Sama Salt to support production at its PVC complex.
Mashal Saoud Al-Kindi, CEO of TA’ZIZ, said, “These long term agreements represent a defining milestone for TA’ZIZ and for the UAE’s industrial growth ambitions. By securing both global demand and reliable local feedstock, we are translating vision into delivery, anchoring world scale chemicals production, strengthening domestic value chains and creating enduring economic value, jobs and supply chain resilience for the UAE.”
Together, these agreements leverage local resources to secure a reliable and sustainable supply of critical raw materials, further strengthening domestic value chains and advancing the UAE’s industrial self sufficiency.
TA’ZIZ is a manufacturing, industrial services, logistics and utilities ecosystem that enables the production of transition fuels and new products across the chemicals value chain, supporting ADNOC’s ambition to become a top three global chemicals player as well as the UAE’s industrial development and economic diversification ambitions.
The TA’ZIZ Industrial Chemicals Zone is set to produce 4.7 million tonnes per annum (mtpa) of chemicals once construction is completed in 2028. This includes a 1 mtpa ammonia plant, a 1.8 mtpa methanol plant and 1.9 mtpa of marketable products from its integrated polyvinyl chloride (PVC) complex. The PVC complex, which produces PVC, ethylene dichloride (EDC), vinyl chloride monomer (VCM), and caustic soda, will be one of the world’s top three largest single site PVC complexes.
Also at the Make it at the Emirates Forum, TA’ZIZ and Alpha Dhabi Holding announced a strategic collaboration agreement for around US$10 bn (AED36.7bn) in capital investment in new industrial chemicals in the TA’ZIZ industrial chemicals ecosystem in Al Ruwais Industrial City, Al Dhafra region of Abu Dhabi.
The partnership could produce up to 14 new chemicals, delivering around 2.2mn tonnes per annum (mtpa) of additional chemical capacity in the TA’ZIZ industrial chemicals ecosystem in Al Ruwais Industrial City. The new chemicals, which include styrene and polystyrenes, acrylic acid and derivates, polyols, MDI, epoxy resins and linear alpha-olefins, are based on domestic demand and could substitute key products currently imported into the UAE, while strengthening local supply chain resilience. The partnership supports the UAE’s national industrial priorities, including the Make it in the Emirates (MIITE) initiative and the country’s industrial strategy, by strengthening domestic manufacturing capability and advancing self-sufficiency in strategically important chemical products.
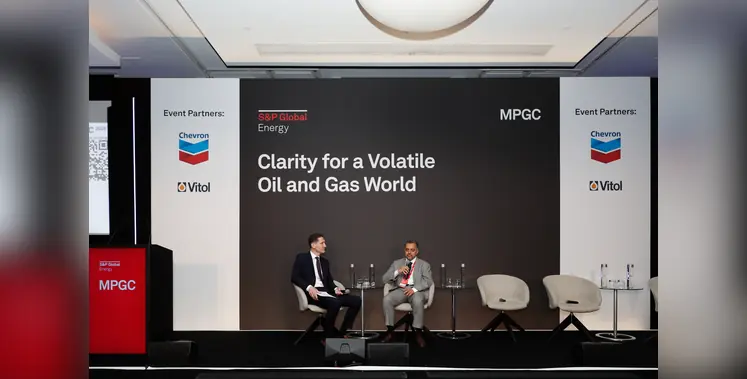
Musaab Al Mulla (right) in conversation with Daniel Evans, VP, global head, fuels & refining, S&P Global Energy. (Image source: S&P Global Energy)
Demand could also drop in markets that have so far weathered the crisis. (Image source: Adobe Stock)
The report highlights the evolution of AI in the energy sector
AI investment and adoption are accelerating across the energy industry as leaders increasingly recognise the potential for it to strengthen energy reliability and resilience in the current volatile environment, according to the third annual Powering Possible report from ADNOC, XRG and Microsoft
The report, entitled Energy Resilience in the Intelligence Era, highlights a significant shift from AI ambition to implementation, with AI delivering growing financial returns as well as creating new infrastructure challenges.
Key findings
• AI becomes a top corporate priority: 62% of energy leaders now rank AI among their top two priorities, up from 42% in 2025, while 89% report increased investment over the past year
• AI investments begin to deliver returns: 63% expect returns on existing investments to cover or exceed costs, rising to 89% for future investments
• Energy demand creates new infrastructure challenges: 74% expect AI to increase energy consumption by 2030, yet only 52% are confident existing infrastructure can meet AI-driven electricity demand – unchanged from 2025. Grid modernisation and smart-grid technologies are the leading investment priority for supporting AI growth, cited by 67% of respondents, followed by energy storage at 42%.
• Importance of energy reliability rises as a measure of AI value: 39% identify supply stability and reliability as AI's most important contribution, up from 26% in 2025, reflecting the current supply volatility. While the share giving cost savings as AI's leading contribution fell from 19% to 13%.
• AI has the potential to accelerate sustainable energy production: 71% of energy leaders expect AI to increase the speed at which the energy sector becomes more sustainable, alongside growing expectations that AI can strengthen resilience, efficiency and the ability to meet rising energy demand. 57% of respondents identify the optimisation of power flows, dispatch and balancing as the area where AI could make the greatest contribution to the energy transition.
• AI moves into everyday operations: The share of organisations deploying integrated agentic AI workflows more than doubled from 15% to 33%, while 60% are piloting or deploying robotics in physical operations, from inspecting infrastructure to performing hazardous tasks.
His Excellency Dr. Sultan Ahmed Al Jaber, ADNOC managing director and Group CEO and executive chairman of XRG said: “AI is creating significant new opportunities for the energy industry to drive greater value, strengthen resilience and improve safety and reliability. At ADNOC, we are embedding AI, robotics and advanced technology across our operations to optimize every barrel, every molecule and every megawatt we produce. As AI scales, energy and technology must advance together.”
Brad Smith, vice chair and president, Microsoft, added, “As AI becomes embedded in the sectors that underpin the global economy, the measure of progress will not be adoption alone, but whether it delivers lasting value while earning public trust. In the energy sector, where reliability and security are fundamental, that requires strong governance, clear accountability and sustained investment in people and skills. Innovation at scale must be matched by responsibility at the same scale.”
The findings underline the need for investment in energy and digital infrastructure to advance together, backed by strong cybersecurity, trusted AI-ready data, common standards, sound governance and a skilled workforce, so AI can be deployed safely and reliably at scale.
Powering Possible 2026 is being published ahead of the fourth ENACT Majlis in Abu Dhabi and ADIPEC 2026 and is based on a survey of almost 400 senior energy and finance leaders.
AVEVA will show how its CONNECT platform unites engineering, operations and enterprise data across the full asset lifecycle. (image source: Adobe Stock)

The webinar will address the risks and realities of dissimilar flange connections. (Image source: Adobe Stock)
Oil Review Middle East is hosting an exclusive webinar by GPT Industries on Dissimilar Flange Connections: Corrosion Risks, Misconceptions, and Practical Solutions, on Thursday 18 June at 9.30am GST
Dissimilar flange connections are widely used across industries, yet they remain a misunderstood and underestimated source of corrosion risk, operational failure, and unexpected cost. This webinar will explore why these connections exist, how they behave in real-world environments, and the critical factors that influence their performance. It will provide practical insight into the risks and realities of dissimilar flange connections, with a focus on corrosion mechanisms, common misconceptions, and effective mitigation strategies to improve reliability and reduce long-term costs.
The session will cover:
✔️ Understanding galvanic corrosion in dissimilar flanges
✔️ The dangers of localised corrosion and its impact on asset reliability
✔️ Common misconceptions around cladding and sealing methods
✔️ Available mitigation strategies, including coatings, bolting practices, and flange isolation kits
✔️ How to apply practical decision-making frameworks based on risk, environment, and lifecycle cost considerations
Register here
GPT Industries is a leading global manufacturer of critical pipeline sealing and electrical isolation products to protect the world’s pipelines, people and environment. With a focus on safety, performance and reliability, the company employs advanced engineering and manufacturing processes to meet the challenging demands of the oil and gas, water/wastewater, hydrogen and construction and infrastructure industries.
Expert presenters will be Rebecca ZImbra – product engineer, GPT Industries, metallurgical/materials engineer with industry, management, and research and development experience and expertise in materials testing, cathodic protection, failure analysis, and weld inspection; and Nick Bander, director – Engineering and Product Management at GPT Industries, an experienced technical team manager with a focus on manufacturing, pipeline corrosion mitigation, oil and gas, energy, and water/wastewater industries, and expertise in team/people development, product application, product design, pipeline, sealing, corrosion, and cathodic protection.
Don't miss this opportunity to gain exclusive practical insights into corrosion risks, mitigation strategies, and decision-making approaches for dissimilar flange connections!
Register here
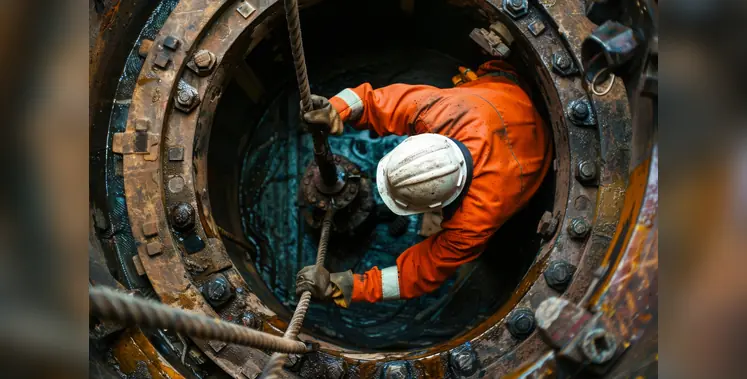
The webinar will explore how organisations can manage confined space risks throughout the entire confined space safety cycle. (Image source: Adobe Stock)

The webinar will explore how drone technology is being used to perform remote NDT inspections, collect critical asset data and create digital twins that support more effective asset integrity management. (Image source: Flyability)
the crisis and the increased focus on energy security are renewing interest in hydrogen and hydrogen-based fuels. (Image source: Adobe Stock)
The conflict in the Middle East has disrupted global production and trade in hydrogen-based products such as fertilisers, fuels and industrial feedstocks, exposing vulnerabilities in supply chains, according to the latest edition of the IEA’s Global Hydrogen Review
The report finds that the crisis and the increased focus on energy security are renewing interest in hydrogen and hydrogen-based fuels, although low-emissions hydrogen remains at a relatively small scale.
Demand for hydrogen worldwide surpassed 100 million tonnes in 2025, according to the report, while production of low-emissions hydrogen grew by 20% to almost 1 million tonnes. However, persistent barriers including high costs, uncertain demand, complex regulations and a lack of infrastructure continue to slow the development of low-emissions hydrogen, putting 2030 targets announced by governments increasingly out of reach.
"The current crisis has highlighted how deeply economies around the world depend on trade in hydrogen-based products and the significant role of the Middle East in those supply chains," said IEA executive director Fatih Birol. "Countries are looking for ways to make their energy systems more resilient and diversified. Low-emissions hydrogen can play an important role in those efforts over time, but stronger policy support and much faster deployment will be needed before it can make a meaningful contribution at scale."
Fertiliser markets have been particularly affected by the conflict in the Middle East, which is home to around one-sixth of global hydrogen production, the majority dedicated to the production of chemicals, fertilisers and refined oil products. The region accounts for more than 10% of global refining capacity, ammonia and urea production, and close to 17% of methanol production.
The region makes up over one-quarter of global trade in ammonia, almost 40% of urea trade and almost 45% of methanol trade, and one-third of its refining capacity is export-oriented. The closure of the Strait of Hormuz has severely disrupted the supply of all these products. The production of hydrogen-based fuels outside the Middle East has also been affected, particularly in Asia, where countries are very dependent on natural gas imports from the Middle East.
Disruptions to production, exports and shipping routes have contributed to shortages and price volatility across global markets with the increase in fertiliser costs posing risks for food supply chains, especially in import-dependent agricultural economies.
Low-emissions hydrogen
Low-emissions hydrogen production grew by 20% in 2025 to reach almost 1 Mt and is set to exceed 1% of global hydrogen production for the first time, but progress is concentrated in a small number of projects. However investment momentum weakened in 2025, with delays to final investment decisions and a shrinking pipeline of projects highlighting the challenges facing the sector.
Despite continued policy support in some markets, low-emissions hydrogen and hydrogen-based products remain significantly more expensive than conventional alternatives in most markets. The pipeline of announced projects for producing low-emissions hydrogen by 2030 has shrunk by around a quarter since last year to 27 million tonnes due to delays and cancellations, and the number of projects likely to become operational by 2030 has fallen significantly.
Demand uncertainty remains a key constraint for scaling up low-emissions hydrogen development, with offtake agreements at low level. This is cited by developers as one of the largest barriers to investment.
Energy-importing countries are scaling clean energy three times faster than energy exporters. (Image source: Adobe Stock)

Abu Dhabi is leading the way in hydrogen development. (Image source: Adobe Stock)
Most Read
-
TotalEnergies will support the refinery with its global oil and feedstock supply capacity. (Image source: Adobe Stock)
-
HE Abdulsalam bin Mohammed Al Murshidi, the president of Oman Investment Authority (OIA)
-
Human factors need to be taken into account when addressing safety. (Image source: Adobe Stock)
-
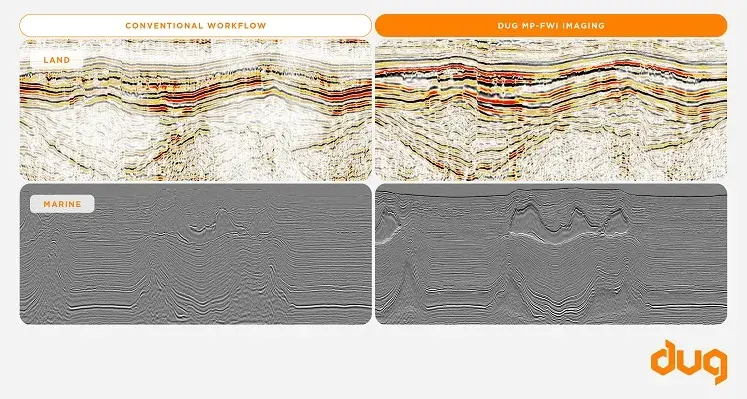
Comparison of conventional workflow with DUG MP-FWI imaging. (Image source: DUG)
-
The programme will optimise asset lifecycle, enhance machinery performance and improve overall reliability. (Image source: Adobe Stock)
-
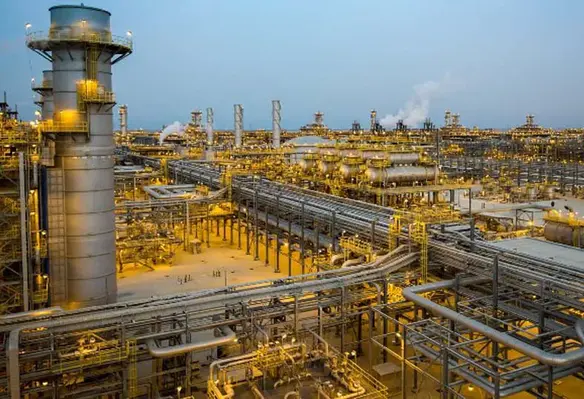
The expansion is expected to increase the plant’s processing capacity from 2.5 to up to 4 billion standard cubic feet per day (bscfd). (Image source: Aramco)
-
TotalEnergies and SONATRACH will develop gas resources in Algeria's north-east Timimoun region, (Image source: Adobe Stock).
-
The programme is designed to strengthen leadership and safety culture in the oil and gas industry> (Image source: Adobe Stock)
-
The partnership will enable HMi Elements to tap into Cobic-Ex’s global network. (Image source: HMi Elements)
-
Block 56 is targeted for commercialisation in 2024. (Image source: Canva)
-
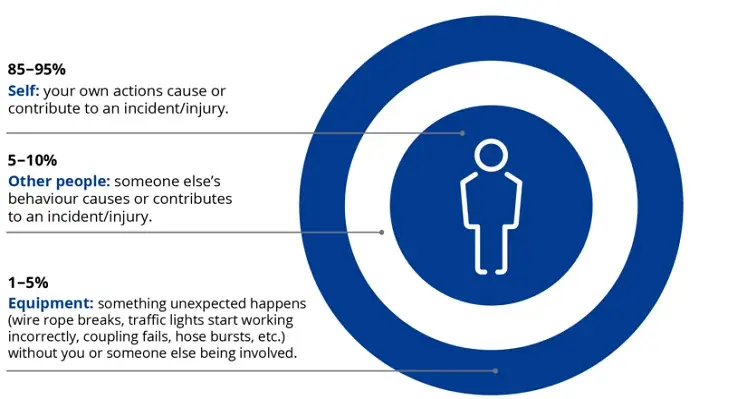
Source: SafeStart
-
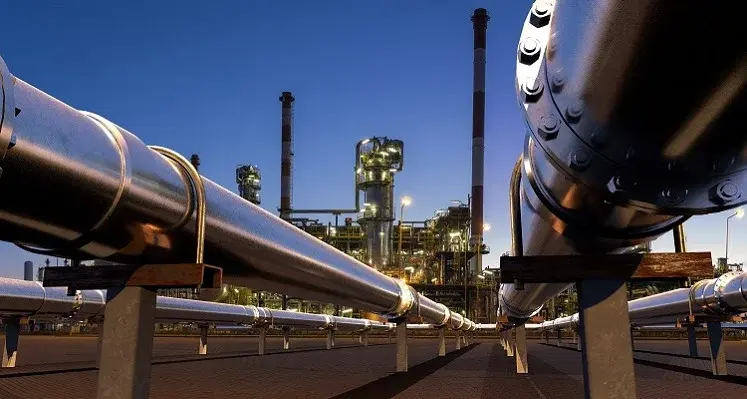
By using analytics to augment and empower the workforce, pipeline operators can optimise operations and improve asset availability. (Image source: Adobe Stock)
- Details
-
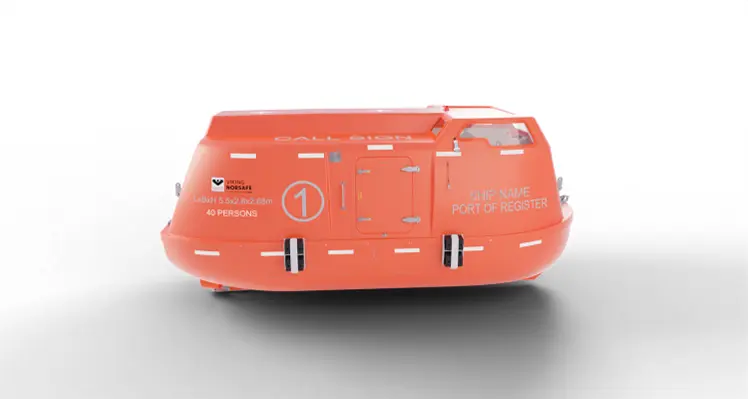
The new range has been launched in response to the demand for compact and lightweight lifeboats. (Image source: VIKING)
-
Operators have never needed to take safety and efficiency more seriously. (Image source: Adobe Stock)
-
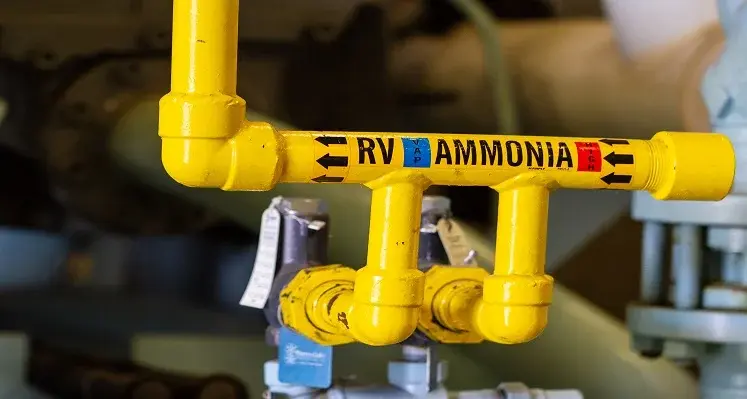
Among other services, KBR will offer proprietary equipment for NCIC's 1,200 metric tonnes per day ammonia plant. (Image source: Adobe Stock)
-
To improve differentiation, hard hats can be customised with different colours and logos. (Image source: MSA Safety)
- Details
-
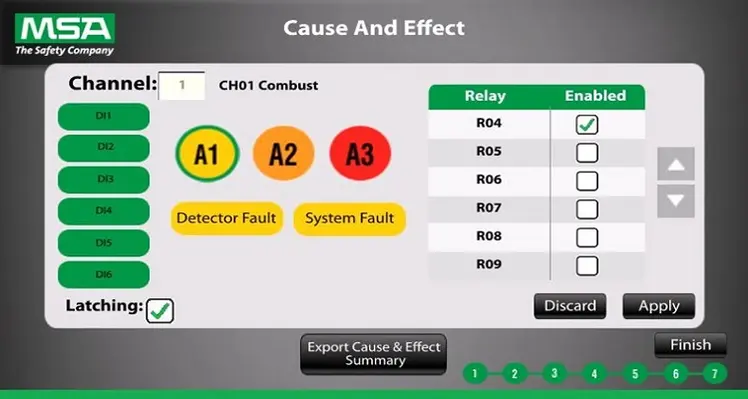
The system can activate notification and hazard mitigation equipment to notify workers and safeguard facilities. (Image source: MSA Safety)
-
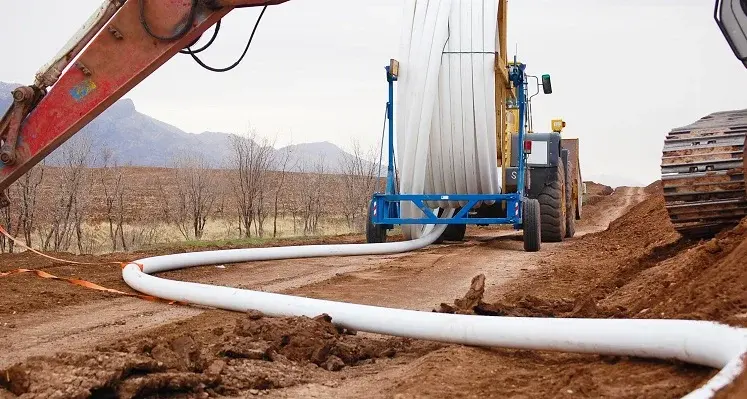
Over 4,000 km of SoluForce pipe has been installed around the world. (Image source: SoluForce)
-
The use of blockchain in the oil and gas sector is set to increase substantially. (Image source: Adobe Stock)
-
Osama Oulabi, general manager, KSA and Middle East, Speedcast. (Image source: Speedcast)
Latest News
-
- Details
-
Tanker shipping is fundamental to global energy trade. (Image source: Noatum Maritime))
-
AVEVA will show how its CONNECT platform unites engineering, operations and enterprise data across the full asset lifecycle. (image source: Adobe Stock)
-
Teledyne Flir will showcase its OGI portfolio at ADIPEC. (Image source: Teledyne Flir)
-
The report highlights the evolution of AI in the energy sector
-
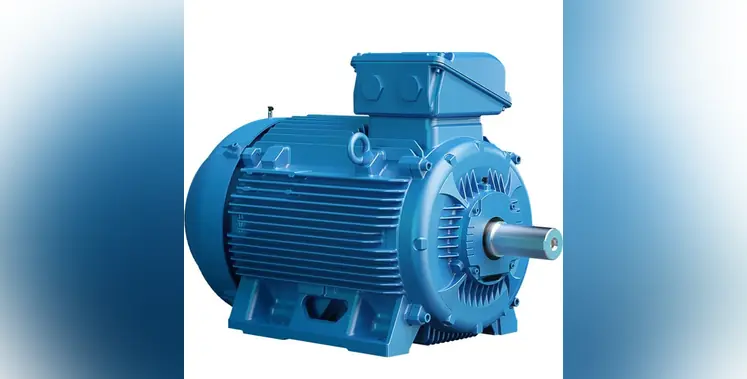
WEG will unveil the W22 prime motor at ADIPEC. (Image source: WEG)
-
First gas was achieved within less than a year from discovery. (Image source: SNOC)
-
Around half of oil and gas producers identify Asia Pacific and the Middle East among their most important customer regions over the next five years. (Image source: Adobe Stock)
-
ADIPEC 2026 will feature more than 2,250 exhibiting companies. (Image source: dmg events)
-
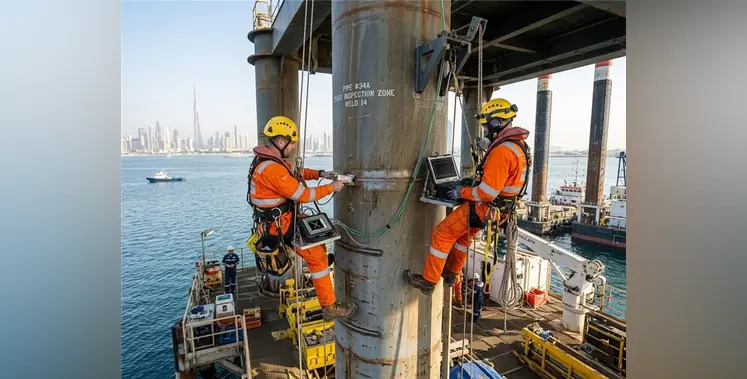
Reaching offshore platforms safely can be a challenges. (Image source: Noatum Maritime)
-
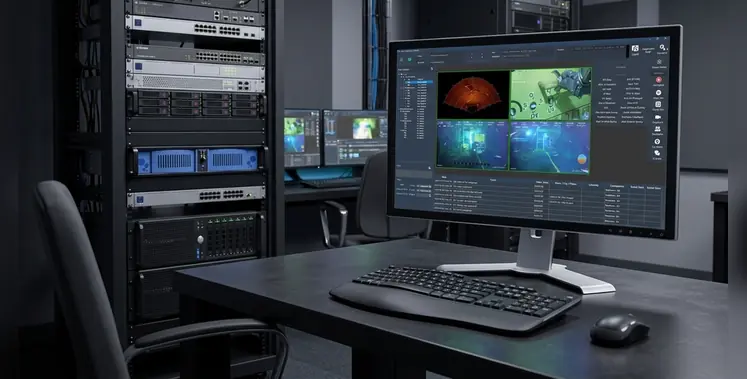
Digital Edge Subsea designs and manufactures video recording and inspection systems for the subsea industry. (Image source: Adobe Stock)
-
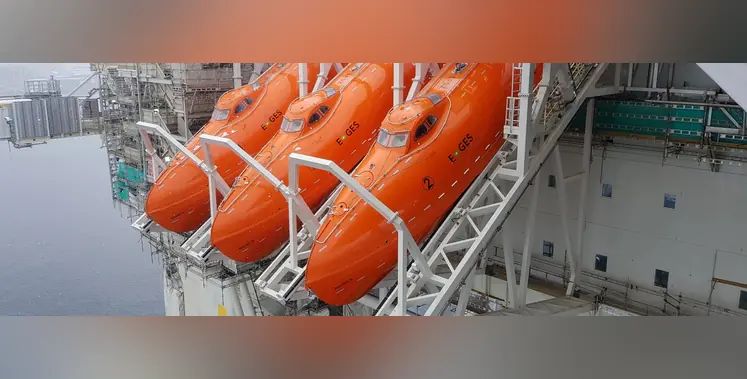
. VIKING Life-Saving Equipment has already delivered its E-GES (Electrical Gravity Escape System) free-fall lifeboats to several well-known companies in the offshore sector.
-
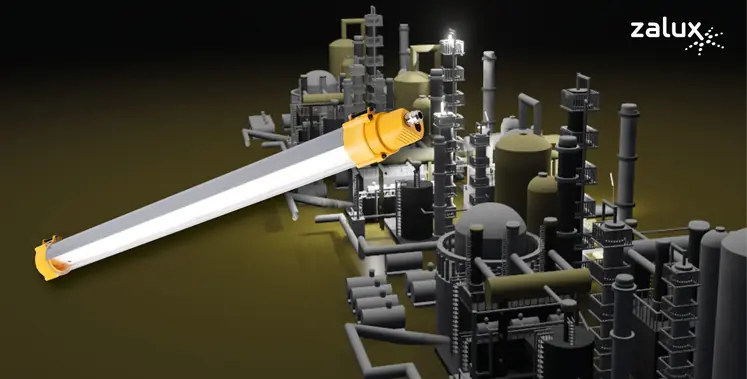
The new STRONGEx G2 luminaire. (Image source: ZALUX)
-
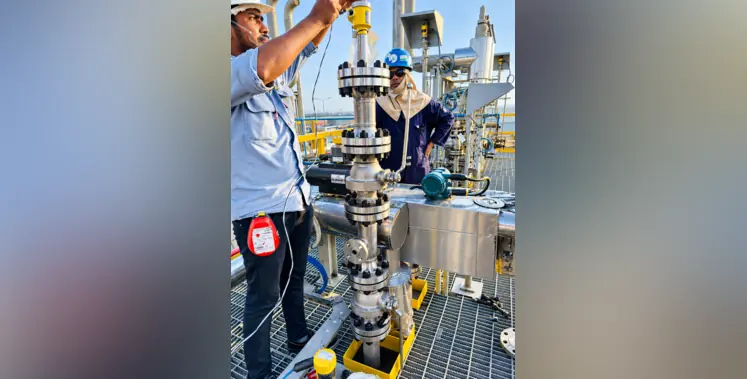
Technicians servicing stainless steel valve assembly. (Image source: VEGA)
-
Sherif Foda, CEO, NESR. (Image source: NESR)
-
The newly established MoU outlines a comprehensive framework designed to integrate the energy sectors of both nations more closely.
-
Nayef Bou Chaaya, vice president, Middle East, Turkey & Central Asia, AVEVA.
More Articles
. VIKING Life-Saving Equipment has already delivered its E-GES (Electrical Gravity Escape System) free-fall lifeboats to several well-known companies in the offshore sector.
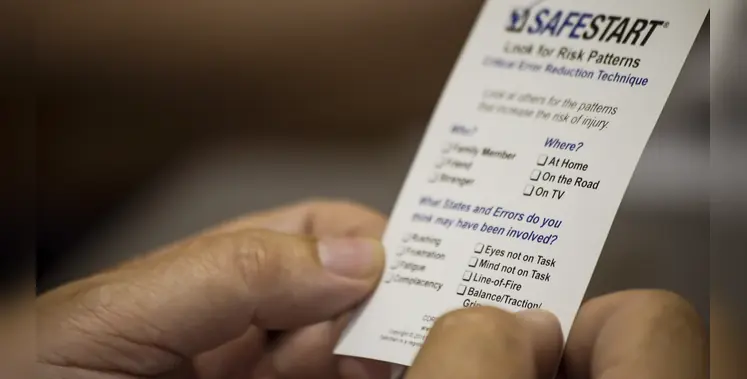
SafeStart is a proven, human factors-based safety programme used worldwide to help organisations reduce injuries and incidents by addressing human error, critical risk exposure and decision-making challenges.
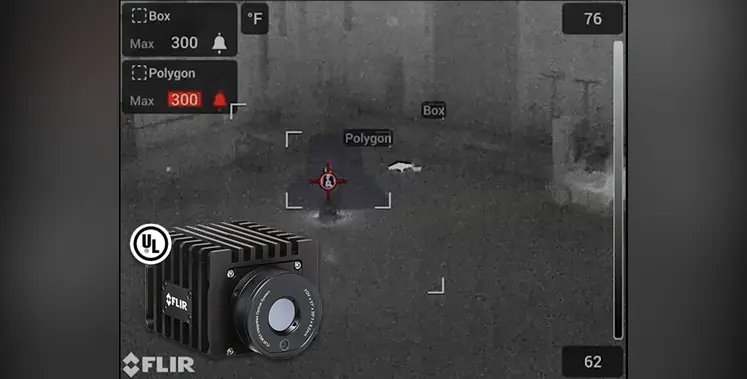
Thermal image fire detection allows for early intervention to prevent fire breaking out. (Image source: Teledyne Flir)
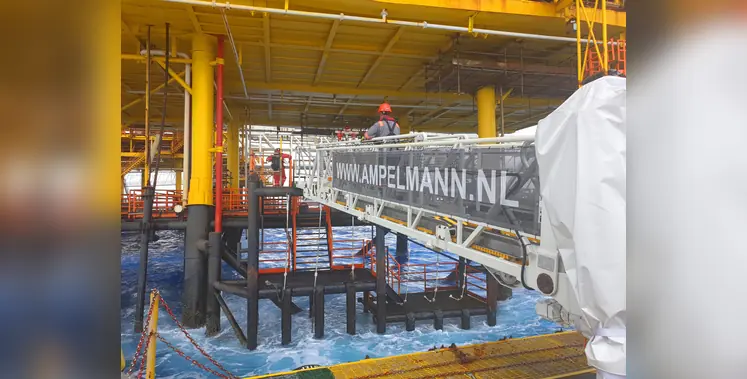
The Ampelmann L-type gangway. (Image source: Ampelmann)

The controller is designed for increasingly complex industrial environments. (Image source: Teledyne Gas and Flame Detection)

Connected technologies are transforming how organisations achieve visibility. (Image source: MSA Safety)
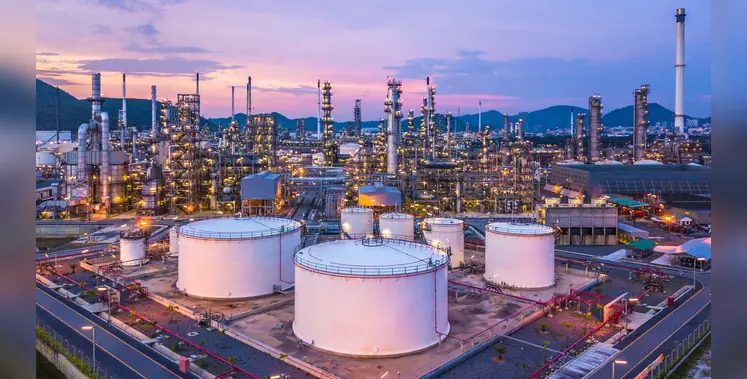
The luminaires are suited to hazardous environments such as petrochemical plants. (Image source: Emerson)
Complacency can lead people to do something they know increases the likelihood of mind or eyes not on task. (Image source: Adobe Stock)
The IMIST standard addresses risks in the energy sector. (Image source: Shutterstock)
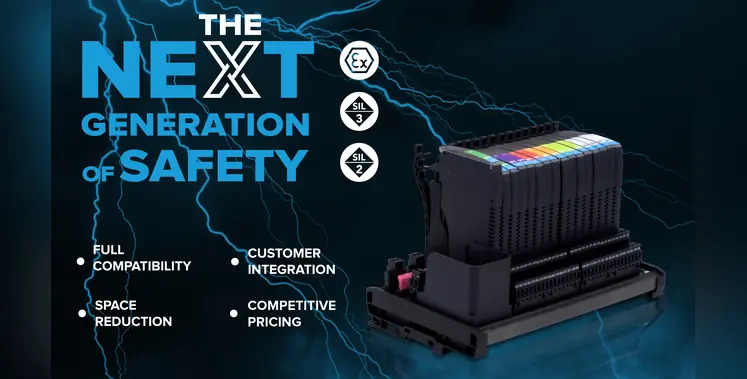
The X1 Series is an advanced universal marshalling system engineered for hazardous areas and high-integrity SIL applications. (Image source: GM International))